


White Commercial's UK Economic & Commercial Property Briefing | OCTOBER 2026
30 October 2026
White Commercial Surveyors monthly view: the UK economy has remained more resilient than confidence surveys suggested, but inflation and financing costs have moved back to the centre of commercial property decision-making. The latest evidence favours prime, efficient and well-located assets, while secondary stock faces a more difficult mix of occupier caution, capex requirements and outward yield pressure.
UK Economy: Resilient Growth, But a Slower 2027 is Now Expected
Official data (15 October): UK GDP grew by 0.1% in August and by 0.7% over the three months to August. Services grew by 0.9% over the three-month period, while construction fell by 1.0%.
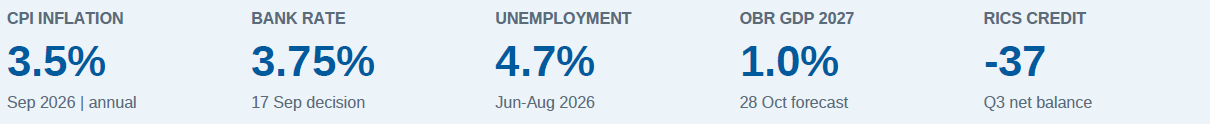
Forecast (28 October): the Office for Budget Responsibility expects GDP growth of 1.2% in 2026, slowing to 1.0% in 2027 before strengthening from 2028. The OBR also expects inflation to peak at 3.8% in Q1 2027.
White Commercial interpretation: the economic backdrop is not recessionary, but the 2027 slowdown and higher-for-longer financing costs argue for more selective occupier, investor and development decisions. For commercial property valuation, income durability and reletting prospects deserve more weight than assumptions of near-term yield compression.
Inflation, Interest Rates and Business Finance
Official data (21 October): CPI inflation rose to 3.5% in September from 3.1% in August. Core CPI rose to 2.8% and services inflation to 3.7%; transport, particularly motor fuels, made the largest upward contribution.
Policy: Bank Rate remains 3.75%. At the September meeting the Monetary Policy Committee voted 6-3 to hold, with three members preferring 4.0%. The next decision is due on 5 November. The Bank has stressed the inflation risks from energy prices and the tightening in borrowing costs faced by households and businesses.
White Commercial interpretation: higher debt pricing feeds directly into investment yields, refinancing and development viability. It also raises the premium on buildings with lower operating costs, reliable income and limited immediate capital expenditure.
Employment, Wages, Business Investment and Confidence
Official data (20 October): unemployment was 4.7% in June-August, regular pay growth was 3.7%, and private-sector regular pay growth was 3.0%. Vacancies fell to 691,000, their lowest level outside the pandemic period since 2014. September payroll data showed little monthly change but remain provisional.
Latest investment baseline (30 September): business investment rose 1.8% in Q2 and was 5.2% above a year earlier, with buildings and structures the largest contributor to quarterly growth.
Business confidence (30 October): Lloyds reported confidence rising six points to 47% in October, above its long-term average. The South East recorded 42%, the East Midlands 44% and West Midlands 42%. ONS business surveys nevertheless continue to show strong concern about energy and fuel costs.
White Commercial interpretation: firms are still investing, but recruitment and cost data show that many boards remain selective. Property decisions are therefore likely to favour operationally efficient, strategically located premises where the business case is clear.
UK Commercial Property Market: Investment Pressure, Occupier Resilience
RICS Q3 UK Commercial Property Monitor (29 October): credit conditions weakened to a net balance of -37% from -23% in Q2, investment enquiries fell to -11%, and short-term capital value expectations weakened to -15%. Overall tenant demand was -8%, but industrial demand was close to flat and prime rental expectations remained positive.
CBRE UK Monthly Index (8 October): all-property capital values fell 0.9% in Q3 while rental values rose 0.5%. This is a clear illustration of the current valuation environment: rental growth can coexist with falling capital values when investment yields move out.
Industrial & Logistics Property: Prime Space Remains Comparatively Defensive
RICS expects prime industrial rents to rise, with a Q3 net balance of +38% nationally and +46% in the Midlands. CBRE recorded industrial rental value growth of 0.4% in Q3, while industrial capital values fell 0.9%.
White Commercial Surveyors view for the M40/M1 corridor: Oxfordshire, Northamptonshire and Buckinghamshire continue to benefit from motorway connectivity, advanced engineering, motorsport, defence, logistics and technology demand. The national evidence supports a widening gap between modern, efficient units and secondary stock. Power capacity, EPC performance, yard depth, loading, labour access and motorway connectivity are increasingly value-critical rather than merely marketing points.
Office property: quality and location are becoming more decisive
RICS reported prime office rental expectations of +41% in Q3, while secondary office rental expectations remained negative. CBRE recorded office rental value growth of 0.7% in Q3 but office capital values fell 1.1%.
White Commercial interpretation: occupiers can remain willing to pay for the right office while investors mark down weaker assets. For Oxfordshire and the wider M40 technology corridor, offices with strong ESG credentials, modern services, good parking and access to skilled labour should be better positioned than older, capital-intensive accommodation. Valuation analysis should distinguish genuinely prime local product from generic office averages.
Retail property: improving investment performance, but occupier pressure remains
Official retail data (23 October): retail sales volumes rose 0.7% in Q3 compared with Q2 and 1.5% year-on-year, although September volumes fell 0.4% month-on-month. CBRE reported that retail was the only mainstream sector to record Q3 capital value growth (+0.2%); retail rents rose 0.5%, led by retail warehouses at +0.8%.
RICS continues to report weaker retail occupier demand and a negative outlook for secondary retail rents. The 28 October Budget introduced additional business-rates support for qualifying retail, hospitality and leisure properties in England from April 2027, including higher Small Business Rates Relief thresholds and a two-year real-terms freeze for qualifying properties.
White Commercial interpretation: this is not a uniform retail recovery. Retail parks, convenience-led formats and strong town-centre pitches can benefit from income yield and restricted supply, while secondary high-street property remains exposed to occupational costs, weaker footfall and capex. Local catchment, covenant and alternative-use potential remain central to value.
Budget 2026: Implications for Commercial Property and Corporate Investment
The OBR has upgraded 2026 GDP growth to 1.2% but expects only 1.0% in 2027. Business investment is forecast to be flat in 2026 and fall 0.5% in 2027 before returning to growth. The Budget also announced additional public financial capacity and a Strategic Sites Accelerator intended to support reindustrialisation and strategic investment sites.
For property markets, the most relevant near-term transmission channels are financing costs, business rates, energy costs and confidence. The Budget offers targeted support, but it does not remove the core valuation challenge created by elevated gilt yields and restrictive lending conditions.
Three Key Takeaways for White Commercial Surveyors
1. UK growth is holding up, but inflation is again the dominant macro risk. The OBR expects 1.0% growth in 2027 and inflation to peak at 3.8% in Q1 2027.
2. Commercial property is separating by quality. Prime offices and prime industrial still have positive rental expectations, while secondary offices and retail are under greater pressure.
3. Capital values and rental values are moving differently. Higher borrowing costs and outward yields mean good occupational performance does not automatically produce capital growth.
What This Means for White Commercial's Clients
Occupiers: assess total occupational cost, not headline rent alone. Energy performance, labour access, power, location and building efficiency can materially affect the business case for a move.
Landlords: invest selectively in specification, presentation and energy performance. In a polarised market, the cost of leaving secondary space unimproved can be greater than targeted refurbishment expenditure.
Investors: prioritise sustainable income, covenant strength, lease terms and realistic reletting assumptions. Higher debt costs reduce the margin for error on yield and exit-value assumptions.
Developers: viability should be stress-tested against finance costs, letting periods and realistic exit yields. Evidence of identified occupier demand is increasingly valuable.
Valuation clients: rental growth and capital growth must be analysed separately. Current RICS and CBRE evidence supports careful treatment of asset quality, lease structure, covenant, capex and local comparable transactions.
White Commercial Surveyors: UK Commercial Property Intelligence for the M40/M1 Corridor
White Commercial Surveyors advises owners, occupiers, investors, lenders and developers across Oxfordshire, Northamptonshire, Buckinghamshire, Warwickshire and the M40/M1 corridor. Our work spans commercial property valuation, industrial and logistics agency, offices, retail property, investment, rent reviews and lease advisory.
The national economic data in this briefing is most useful when combined with local evidence: current enquiries, completed transactions, incentive packages, rental tone, investment yields, development pipelines and occupier requirements. That is where White Commercial adds value - translating UK economic change into practical commercial property decisions in our regional markets.

Chris White
Managing Director

Harvey White
Commercial Property Advisor